|
Most experienced lenders know the feeling.
January starts strong. February arrives, tax refunds
begin hitting customers' bank accounts, and something
changes. Applications may slow, existing borrowers
pay off loans, and outstanding receivables begin
shrinking.
Then, as the year progresses, loan demand
starts building again.
By the fourth quarter, many lenders are dealing
with an entirely different business environment.
Is this simply industry folklore, or is there
actual evidence supporting predictable seasonal
patterns in subprime consumer lending?
There is more evidence than you might think.
In researching this question, I reviewed IRS
statistics, Consumer Financial Protection Bureau
(CFPB) studies, and historical SEC filings from
consumer lending companies.
What emerged was a consistent picture:
consumer lending is seasonal, tax refunds are an
important driver, and the second half of the year
frequently looks very different from the first.
But there is a catch.
The available evidence does not establish a
single, reliable month-by-month seasonal index
for every payday, car title, installment, and
line-of-credit lender operating in the
United States.
That distinction matters. It is the difference
between recognizing an industry pattern and
building a defensible operating forecast.
The Evidence: Lenders Have Been Telling
the SEC This for Decades
One of the strongest pieces of evidence comes
from the lenders themselves.
In a 2009 Form 10-K, publicly traded payday
lender First Cash Financial Services described
historically strong payday loan demand in January
and during the fourth calendar quarter.
The company also described declining demand
during the remainder of the first quarter and
early second quarter as borrowers received
income tax refunds. Its loss ratios historically
tended to be higher in the second and third
quarters. [1]
That's not a recent theory. It was a formal
disclosure based on years of lending operations.
And First Cash wasn't alone.
Advance America described a somewhat different
quarterly pattern in its historical SEC filings,
reporting stronger payday demand during the third
and fourth quarters and weaker demand during
the first quarter.
[2]
Notice the distinction.
One operator specifically identified January
as a strong month before refund-driven weakness
set in. Another described the first quarter
as generally its weakest.
Both observations can be true.
A strong January doesn't necessarily produce
a strong first quarter when February and March
weaken.
The pattern also extends beyond traditional
payday lending.
OneMain Holdings has described seasonal
consumer lending demand, with the first quarter
generally weaker and demand increasing later
in the year. The company also recognizes that
economic conditions can disrupt historical
patterns. [3]
These disclosures are company-specific,
not a nationally representative
statistical sample.
Nevertheless, when multiple lending companies
independently describe similar patterns across
many years, those observations deserve
serious consideration.
The Tax Refund Effect: Hundreds of Billions
of Dollars Entering Household Accounts
If you want to understand subprime lending
seasonality, start with tax refunds.
|
$241.7 Billion
Federal income tax refunds issued for current-year
returns through April 3, 2026, covering
approximately 69.8 million refunds.
Source: IRS [4]
|
That is an enormous seasonal movement of money.
Under the PATH Act, the IRS cannot release
refunds associated with returns claiming the
Earned Income Tax Credit or Additional Child
Tax Credit before February 15.
This creates an important difference between
January and early February versus late February
and March for eligible refund recipients.
[5]
Think about what this means for a consumer
with limited savings, high credit card
utilization, and little access to conventional
credit.
In January, that borrower might need a few
hundred dollars for an unexpected expense.
In March, the same borrower might receive
several thousand dollars from a tax refund.
For lenders, several outcomes become plausible:
- Existing borrowers may repay loans early.
- Some customers may temporarily avoid new borrowing.
- Collections may improve as household liquidity increases.
- Outstanding receivables may decline even when new
lending continues.
These are reasonable operating hypotheses.
IRS data alone do not tell us exactly how many
payday or title loans are avoided or repaid
because of refunds.
Tax season can potentially influence
both new originations and repayment activity.
A lender measuring only funded loans may
miss half the story.
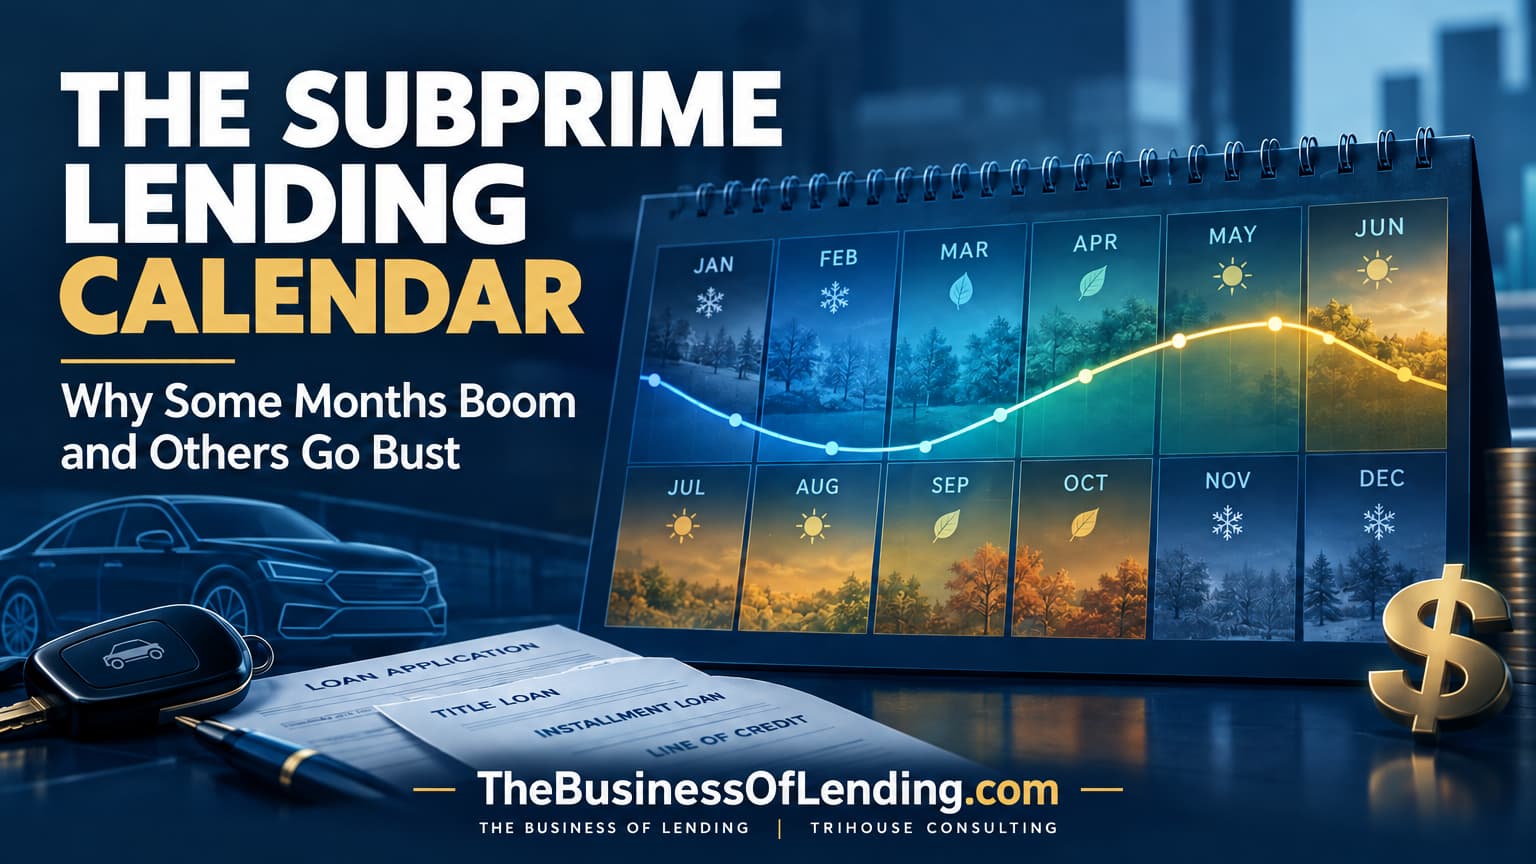
The 12-Month Lending Calendar:
My Working Assessment
Based on the SEC disclosures, IRS refund
patterns, and the structure of these lending
products, here is my working interpretation
of the year.
This is a directional operating hypothesis,
not a measured national monthly origination
index.
| Month |
Working Outlook |
| January | Relatively strong |
| February | Transition toward weakness |
| March | Likely among the weakest |
| April | Potentially subdued |
| May | Potential recovery |
| June | Improving or stable |
| July | Potentially stronger |
| August | Potentially strong |
| September | Moderate to strong |
| October | Stronger seasonal period |
| November | Potentially strong |
| December | Potentially strong |
Research qualification: These assessments are
directional, not independently measured monthly
national loan volumes.
My greatest confidence is in the broad
quarterly pattern, not the exact ranking of
individual months.
March is a reasonable candidate for a weak
origination month. But available national
product-level evidence is insufficient
to declare it the weakest month for every
lender.
Likewise, a strong fourth quarter does not
automatically justify increasing advertising
or changing underwriting standards.
Not All Subprime Loan Products
Follow the Same Calendar
Payday Loans
Single-payment payday loans are closely
connected to paycheck timing and short-term
liquidity needs.
CFPB research found that more than 80%
of payday loans in its studied portfolios
were rolled over or followed by another
loan within 14 days.
[6]
That means one borrower may generate multiple
funded transactions within a relatively
short period.
Operators should distinguish new customer
demand from repeat borrowing and refinancing.
Car Title Loans
Title loans introduce another dimension:
the borrower has pledged a vehicle
as collateral.
In a 2016 study, the CFPB found substantial
same-day reborrowing among single-payment
vehicle title borrowers.
[7]
Refund-season cash inflows could potentially
support more complete payoffs, but the
national magnitude remains unverified.
Installment Loans
Installment loans distribute repayment over
multiple scheduled payments.
An installment lender may experience slower
new originations while receiving substantial
principal and finance-charge payments from
earlier loan vintages.
Its cash-flow pattern therefore depends
on the existing portfolio as well as
current customer demand.
Lines of Credit
For revolving credit, an existing borrower
may draw additional funds without opening
a new account.
Operators should therefore measure new
accounts, repeat draws, utilization, and
repayments independently.
Five Operating Mistakes Seasonality Can Expose
1. Treating Every Month as Financially Identical
Many operators divide annual growth targets
by 12 and expect relatively consistent
monthly results.
A weak March might be normal seasonality,
an underwriting issue, a marketing problem,
or some combination.
Recommendation: Establish monthly
targets using comparable historical
performance instead of equal allocations.
2. Mistaking Lower Receivables for
Lower Customer Demand
Suppose your company funds $900,000
in principal during March but collects
$1.1 million in principal.
Outstanding principal declines by $200,000,
before other adjustments.
That doesn't mean originations disappeared.
It means principal collections exceeded
disbursements.
Recommendation: Track funded principal,
principal collected, early payoffs, and
ending balances separately.
3. Ignoring Seasonality in Delinquency Analysis
Historical corporate filings identify
seasonal variations in loss ratios and
delinquency.
But changes in loan age, product mix, and
borrower composition can affect aggregate
delinquency rates.
Recommendation: Review first-payment
defaults, 30-day and 60-day delinquency,
charge-offs, and recoveries by loan vintage.
4. Spending the Same Marketing Dollars
Every Month
If demand changes seasonally, acquisition
economics may also change.
But lower demand does not automatically
mean marketing should be reduced.
Competitive intensity and conversion
rates also matter.
Recommendation: Compare acquisition
cost, funded conversion, and subsequent
credit performance by calendar month.
5. Failing to Prepare for Seasonal
Capital Requirements
In a high-origination month, a lender may
need additional funding even as revenue
increases.
During periods of unusually high principal
repayments, cash can increase while the
portfolio contracts.
Recommendation: Build a rolling
13-week cash forecast covering disbursements,
principal collections, collected finance
charges, expenses, and credit losses.
What I Would Do If I Were Operating
a Lending Portfolio Today
I would not begin by purchasing another
piece of software.
I'd start by asking my accounting and
operations teams for five years of
monthly portfolio records, if available.
Not merely balances or revenue.
I would want funded loan counts, unique
new borrowers, repeat borrowers, principal
funded, early payoffs, collections, and
losses, separated by product.
Then I would compare January with January,
March with March, and October with October.
I'd adjust for new stores, closed stores,
pricing changes, regulatory changes,
and major shifts in underwriting.
Next, I would calculate a seasonal index
for each key metric.
If March consistently measured 82 on
an index where the monthly baseline equals
100, that would imply 18% below the
modeled baseline.
The number 82 is illustrative, not an
industry statistic.
And what if your lender doesn't follow
the traditional pattern?
That's valuable information too.
My Bottom Line
The evidence is persuasive that consumer
lending seasonality is real.
SEC disclosures from payday and installment
lenders describe recurring changes in loan
demand, balances, and credit performance.
IRS statistics document the enormous scale
of seasonal refund cash flows.
CFPB research explains why repeat borrowing
and product structures complicate
volume comparisons.
But we still lack a reliable national
month-by-month dataset establishing precise
seasonal origination changes for all four
high-APR loan products.
I am highly confident that a broad seasonal
pattern exists. I am considerably less
confident about exact monthly changes
without seeing the portfolio data.
|
Seasonality isn't an excuse for weak results.
It's a variable you should understand,
measure, and plan around.
|
If your business slows every March,
perhaps that is normal.
But if your company slows significantly more
than comparable competitors, that's another
problem worth investigating.
And if November produces record originations
but disproportionate losses, celebrating
that record month may be premature.
The objective isn't simply to fund
more loans during busy months. It is to
earn more money, after losses and operating
costs, throughout the entire year.
That's the business of lending.
Jer Ayles
Trihouse Consulting
TheBusinessOfLending.com
Jer@TheBusinessOfLending.com
Sources & Evidence
[1]
First Cash Financial Services, Inc.
Form 10-K for fiscal year 2009.
SEC filing.
[2]
Advance America, Cash Advance Centers, Inc.
Historical Form 10-K.
SEC filing.
[3]
OneMain Holdings, Inc. 2025 Form 10-K.
SEC filing.
[4]
Internal Revenue Service.
Filing Season Statistics, week ending April 3, 2026.
IRS statistics.
[5]
Internal Revenue Service.
Filing Season Statistics, week ending February 13, 2026.
IRS statistics.
[6]
Consumer Financial Protection Bureau (2014).
CFPB Data Point: Payday Lending.
CFPB study.
[7]
Consumer Financial Protection Bureau (2016).
Single-Payment Vehicle Title Lending.
CFPB study.
Research note: Corporate SEC filings contain
company-specific historical observations,
not a national lending census. The monthly
outlook in this article is a directional
assessment rather than a measured national
seasonal index.
A Question for Fellow Lenders
Does your portfolio follow the familiar
pattern of a strong January, tax-season
slowdown, and growing demand later in
the year?
Or do your title, installment, and
line-of-credit portfolios behave differently?
Share Your Experience With Jer
|
|