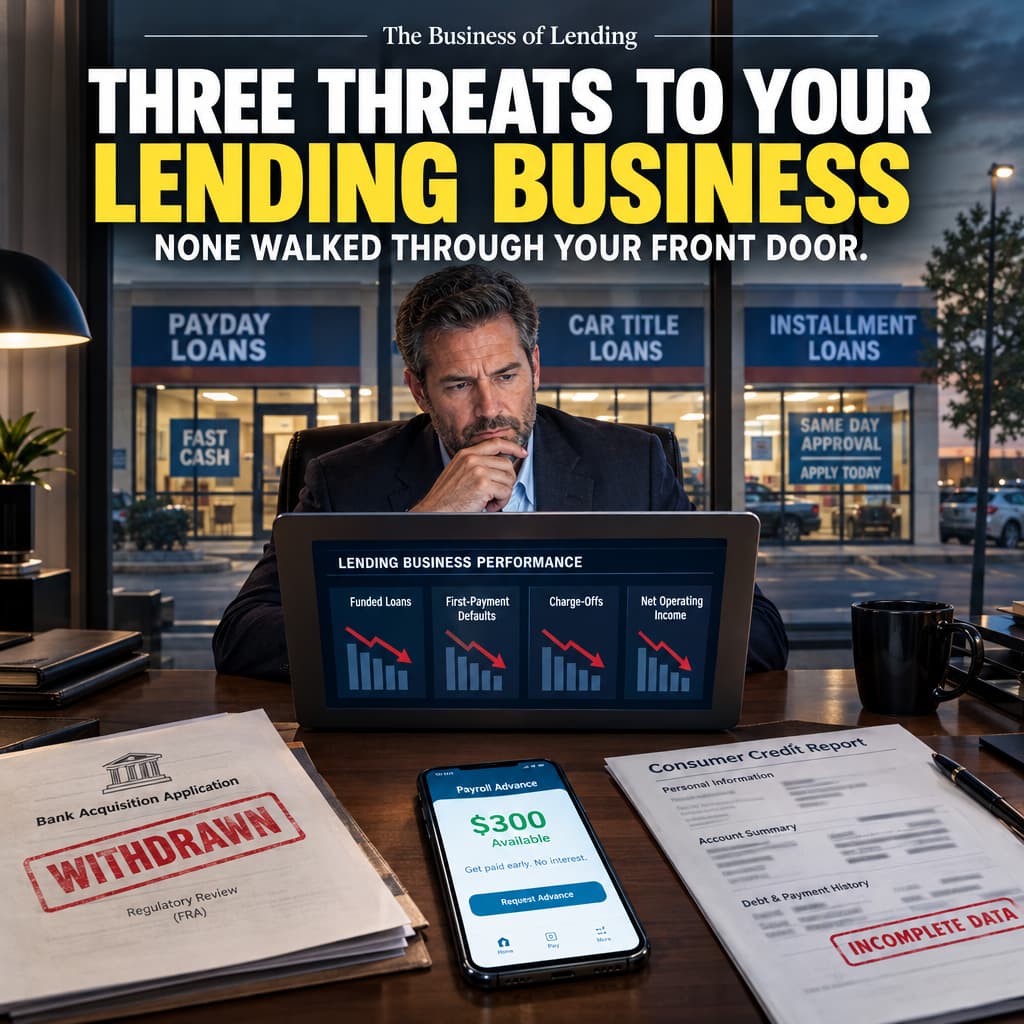
THREE THREATS TO YOUR LENDING BUSINESS. NONE OF THEM WALKED THROUGH YOUR FRONT DOOR.
A major lender loses 23% of its market value in one day. A payroll app threatens the repeat customers your stores depend on. And changes to medical-debt reporting could leave your underwriting team with less information about a borrower's obligations.
These aren't three unrelated news stories. They're three ways your lending business could lose money without anyone noticing until the monthly numbers come in.
Keep reading. I'll show you what happened, where the financial exposure lies, and five questions you should be asking your managers this week to protect loan volume, reduce defaults, and improve NOI.
I've spent more than 20 years in the business of lending money to strangers.
Payday loans. Car title loans. Installment loans. Storefronts. Online lending.
And I've learned something that doesn't change:
The biggest threats to a lending business aren't always the competitors you can see.
Sometimes it's a regulator.
Sometimes it's a technology company that gets to your customer before you do.
And sometimes it's an underwriting decision made with incomplete information.
Let's talk about all three. More importantly, let's talk about what they mean for your money.
1. ENOVA LOST 23.4% IN ONE DAY. ITS REVENUE OUTLOOK WAS STILL GROWING.
On September 14, Enova International announced it was withdrawing its applications to acquire Grasshopper Bancorp.
The deal was worth approximately $369 million.
The prize was a national bank charter.
And that charter could have opened strategic opportunities unavailable to Enova under its existing structure.
The following trading day, Enova stock fell $53.11 per share.
That's 23.4% gone in one session.
Here's what makes this interesting.
On the same day Enova announced the withdrawal, management reaffirmed its guidance:
- Third-quarter revenue growth: approximately 25%.
- Third-quarter adjusted earnings-per-share growth: approximately 30%.
- Full-year revenue growth: 20% to 25%.
- Full-year adjusted EPS growth: 30% to 35%.
Those were management forecasts, not reported final results.
Nevertheless, the operating business was still projecting substantial growth.
Then, on October 7, Wolf Popper LLP announced an investigation into potential investor claims involving Enova.
An investigation is not a finding of wrongdoing. No operator should confuse the two.
But the market reaction had already delivered a message.
A business can be performing well operationally and still take a beating when an important strategic assumption collapses.
What should a payday, title, or installment lender learn from this?
Don't build your future around regulatory permission you haven't received.
Maybe you're depending on a bank partnership.
Maybe you're considering a new state.
Maybe you're planning to change your product structure based on a favorable interpretation of existing law.
Fine. Explore it.
But don't confuse a potential opportunity with an operating asset.
Your existing licenses, underwriting performance, collections results, customer relationships, and profitable loan portfolio are assets you can measure today.
A pending regulatory approval is not.
And I would take this one step further.
Before spending serious money on a new lending structure, ask:
- What happens to the economics if the regulatory assumption fails?
- How much capital have we committed?
- What happens to customer acquisition costs?
- Can we still fund and service the loans legally and profitably?
- Can the company survive the delay or rejection?
The Enova episode doesn't prove every bank-charter strategy is a mistake.
It proves the downside of regulatory dependency can be enormous.
OPERATOR TAKEAWAY:
Growth built on uncertain permission needs a contingency plan. Growth built on proven unit economics gives you something to stand on.
|
2. YOUR NEXT COMPETITOR MAY NOT NEED A STORE, A LOAN APPLICATION, OR EVEN A TRADITIONAL CREDIT PRODUCT.
On October 6, McGuireWoods announced an interactive tracker covering earned wage access legislation across all 50 states.
According to the firm, 12 states have passed EWA laws or regulations, with additional legislation pending.
That ought to get the attention of anyone operating a payday, installment, or line-of-credit business.
Why?
Because earned wage access is attacking a familiar consumer problem.
The customer is employed.
The paycheck is coming.
The checking account is running low.
And the customer needs $300 before payday.
Sound familiar?
We've been serving variations of this customer for decades.
Except now, depending on the employer and provider, the consumer may be able to access wages already earned through an app connected to payroll.
No trip to your storefront.
No comparison of local lenders.
No conversation with your CSR.
They press a button.
And some of the borrowing demand that might have reached your business never arrives.
The regulatory difference matters.
On December 23, 2025, the CFPB issued an advisory opinion explaining that certain narrowly defined Covered EWA products are not credit under Regulation Z.
The qualifying characteristics include advances limited to wages actually earned and verified through payroll data, recovery through payroll processes, no recourse against the worker, and no individual credit-risk assessment.
That does not mean every EWA product is exempt from lending laws.
It doesn't mean state law disappears.
And it certainly doesn't mean every provider can call a loan an earned-wage advance and escape regulation.
But it does mean that some EWA programs operate under a materially different federal regulatory framework from conventional consumer loans.
While a licensed payday lender manages examinations, disclosures, renewals, collections, and state-specific requirements, some qualifying EWA products can serve overlapping consumer needs without being Regulation Z credit.
Think about what that means competitively.
Your repeat customers may be the first opportunity.
Consider a hypothetical storefront lender.
The company funds 1,000 loans per month.
Four hundred are repeat-customer transactions.
Let's say the average repeat loan produces $90 in contribution after direct variable costs and expected credit losses.
Now suppose 10% of repeat-loan transactions shift to EWA or another alternative.
That's 40 fewer funded transactions.
At $90 apiece, that's $3,600 in monthly contribution at risk.
Annualized: $43,200.
That's one hypothetical location.
Multiply that by 20 stores, assuming the same economics, and you're talking about $864,000 in annual contribution.
This is not a forecast of EWA displacement. It's an example showing why a relatively small shift in repeat business deserves management attention.
And here's the dangerous part.
You probably won't receive a notification that says:
"Congratulations. Your borrower just discovered earned wage access."
Instead, your numbers quietly change.
New-customer applications soften.
Repeat-loan frequency declines.
Funded transactions flatten.
Marketing costs per funded customer rise.
And your district manager tells you the stores need to make more outbound calls.
Maybe they do.
But you can't fix a market-share problem by yelling at your CSRs.
What should an operator measure?
Start comparing cohorts, not just monthly totals.
- New-customer applications, approvals, and fundings.
- Repeat transactions per customer over 30, 60, and 90 days.
- Previously active borrowers who stop returning.
- Changes by store, product, employer concentration where lawfully available, and customer tenure.
- Customer acquisition cost per profitable funded loan.
And start asking customers a simple question:
"What other options have you used when you needed money between paychecks?"
That answer may tell you more about your future competition than another mystery shop of the payday store three miles away.
One more thing.
EWA isn't necessarily bad for consumers. Access to already-earned wages can reduce the need for borrowing, depending on fees and usage patterns.
Our job as operators isn't to wish away a product that may better serve some customers.
Our job is to understand what customer needs remain, and build a business that serves them profitably and responsibly.
OPERATOR TAKEAWAY:
The competition isn't always another lender. Sometimes it's a better-timed solution to the same cash shortage.
|
|
ADVERTISEMENT | AFFILIATE PARTNER
Looking for lending leads or opportunities to monetize traffic?
Explore RoundSky's opportunities for lenders and affiliates.
Learn More About RoundSky →
Affiliate disclosure: I may earn a commission from qualifying activity through this link.
|
3. THE CREDIT FILE DIDN'T GET CLEANER. IT GOT QUIETER.
Washington, D.C. enacted the Medical Debt Mitigation Amendment Act of 2026, effective August 20.
Among other provisions, the law restricts medical-debt reporting, caps annual interest on medical debt at 3%, and prohibits wage garnishment for medical debt when household income falls below 500% of the federal poverty level.
Other states have adopted medical-debt reporting restrictions as well.
Now think about what that means for underwriting.
Your applicant has a credit score of 610.
Regular employment.
Monthly take-home income of $3,400.
Maybe an active checking account with direct deposits every two weeks.
The bureau report looks acceptable under your current policy.
But the borrower also has a medical payment arrangement consuming $275 every month.
Depending on the law, reporting practices, and credit-file contents, you may not see that obligation in the bureau data.
The debt may still exist.
The payment obligation may still affect monthly cash flow.
The absence of a reported collection does not automatically mean the absence of financial stress.
Before we go further, there's an important distinction.
Medical collections were never a perfect predictor of future loan performance. And removing medical debt from reporting does not automatically mean default rates will increase.
That's a hypothesis operators need to test, not a conclusion we should pretend is established.
But there's a bigger issue I've talked about for years.
We confuse income with repayment capacity.
A borrower earns $4,000 a month.
Great.
How much is left after everything else gets paid?
Rent.
Auto payment.
Insurance.
Utilities.
Credit cards.
Child support.
Existing loan payments.
Medical expenses.
Now add your proposed payment.
That's the number that interests me.
Not the gross paycheck.
Not just the credit score.
The money available when our payment actually comes due.
Here's how a simple underwriting decision goes sideways.
Take two hypothetical applicants.
Both show $4,000 in monthly take-home pay.
Both have a 610 credit score.
Both request a $1,000 installment loan.
Applicant A has recurring monthly obligations of $2,600, leaving $1,400 before the proposed loan payment and other spending not captured.
Applicant B has recurring monthly obligations of $3,650, leaving only $350 on the same basis.
Same income.
Same score.
Same requested loan.
Very different cash-flow cushions.
Now imagine both are approved for a $200 monthly payment.
Applicant A has $1,200 left after those identified obligations and the new payment.
Applicant B has $150.
That doesn't prove Applicant B will default.
But it should change how you assess repayment capacity.
The solution isn't simply tightening the score cutoff.
If a particular type of information disappears from credit reports, dropping your minimum score from 600 to 580 or raising it to 640 doesn't necessarily solve the underlying question.
You need to know which cash-flow variables actually predict losses.
That can include, subject to applicable law and proper customer authorization:
- Verified net deposits and income consistency.
- Existing recurring payment obligations.
- Returned ACH transactions and overdraft patterns.
- Volatility in account balances.
- Timing between income deposits and scheduled repayments.
- Existing debt payments and the customer's actual remaining cash flow.
Bank transaction analysis can be useful, but don't pretend it's perfect either.
A medical bill paid in cash won't necessarily appear.
A third party might make the payment.
Some transactions will be difficult to categorize.
And operators must respect legal restrictions on acquiring, using, and interpreting consumer information, including medical information where applicable.
The goal isn't to build a surveillance system.
It's to make better, lawful, fair, and more consistent credit decisions.
And here's what I want the underwriting manager to answer.
- Which approved applicants miss their first payment?
- What cash-flow characteristics do they share?
- Do those patterns differ between new and repeat borrowers?
- Which exceptions create incremental profit, and which create losses?
- Which stores are approving borrowers with weaker repayment capacity than the rest of the company?
- Which loan sizes, repayment dates, or payment structures are associated with unnecessary defaults?
You don't need another pretty dashboard.
You need a report that tells you where money is leaking.
OPERATOR TAKEAWAY:
A bureau report is one source of information. Repayment capacity is the decision you're trying to make.
|
THE $100,000 QUESTION: WHAT'S HAPPENING INSIDE YOUR OWN LOAN PORTFOLIO?
Here's where I bring all three stories together.
A regulatory strategy can fail.
A competitor can take transactions you never see.
A credit file can leave out information relevant to your underwriting.
And management can spend six months discussing all three without changing a single operating decision.
That last one bothers me more than the headlines.
Because nobody pays you for understanding the lending industry.
They pay you, directly or indirectly, for operating a business that makes good decisions with capital.
Let's put some numbers to it.
Imagine a lender funding $1 million in principal per month.
Suppose a better underwriting and repayment-alignment process reduces realized net credit losses by one percentage point of funded principal, without materially reducing profitable originations or adding offsetting costs.
That's $10,000 in monthly loss reduction.
Or $120,000 annually.
Now suppose the same operation finds a way to recover $5,000 per month in otherwise lost contribution from qualified, profitable repeat transactions.
That's another $60,000 annually.
Together, those improvements would represent:
$180,000 IN ANNUALIZED OPERATING CONTRIBUTION.
Before implementation costs and other offsets.
Those are illustrative assumptions, not industry averages or promised outcomes.
But this is the kind of math I want operators doing.
Not just how many applications arrived.
Not just how many loans we funded.
And certainly not whether the store hit some arbitrary loan-count target.
I want to know: How many profitable loans did we make, how much money did we actually collect, and how much contribution did we preserve?
That's the business.
Everything else should support it.
FIVE QUESTIONS FOR YOUR MONDAY MANAGEMENT MEETING
If I were sitting in your conference room this morning, I'd put these on the screen:
1. REGULATORY EXPOSURE
Which part of our next 12 months of planned growth depends on a regulatory approval, legal interpretation, bank partner, or lending structure outside our control?
2. CUSTOMER LEAKAGE
Is our repeat business growing, flat, or shrinking after we account for seasonality, store maturity, and changes in customer acquisition?
3. UNDERWRITING QUALITY
Are first-payment defaults increasing in particular stores, products, customer segments, or underwriting-exception categories?
4. DATA QUALITY
What important repayment-capacity information do we not collect, cannot lawfully use, or fail to analyze?
5. NET OPERATING INCOME
If we could improve only one operating variable over the next 90 days, which would produce the largest measurable improvement in risk-adjusted contribution?
Assign an owner.
Set a deadline.
Measure the result.
Otherwise, it's another management meeting where everybody drinks coffee and agrees that things are changing.
THE BOTTOM LINE
Enova reminds us that regulatory strategy carries risk.
Earned wage access reminds us that owning a storefront doesn't mean owning the customer.
Medical-debt reporting changes remind us that a credit file is not the entire financial picture.
None of these developments means the payday, title, or installment lending business is finished.
Far from it.
There are still millions of Americans whose legitimate credit needs are not being met by traditional banks.
But demand alone doesn't make a lending business profitable.
You have to acquire the right customers, underwrite the right risks, collect the money, and protect the margin.
I've spent much of my working life lending money to people other lenders didn't want to serve.
One thing that experience taught me:
The money isn't made when you approve the loan.
It's made when the customer pays it back, the numbers work, and you have enough capital left to do it again tomorrow.
Don't mistake loan volume for profit.
See you next issue.
Jer Ayles
The Business of Lending Money to Strangers
TheBusinessOfLending.com
WANT MORE OPERATOR INTELLIGENCE?
The Business of Lending Newsletter - Free
Practical analysis of payday, title, installment lending, underwriting, collections, regulation, and the numbers that determine whether your company makes money.
LENDING TO THE MASSES: THE 500+ PAGE OPERATOR'S BIBLE
My comprehensive resource covering the business of lending money to strangers, including storefront operations, underwriting, collections, and lending economics.
Built for people who actually run lending businesses.
SOURCES AND FURTHER READING
1. Enova International - September 2026
Enova Withdraws Grasshopper Bank Acquisition Applications
2. Wolf Popper LLP - October 7, 2026
Enova Investor Investigation Announcement
3. McGuireWoods - October 6, 2026
50-State Earned Wage Access Legislation Tracker
4. CFPB Earned Wage Access Advisory Opinion
CFPB Draws Line Between Earned Wage Access and Credit
5. Washington, D.C. Medical-Debt Legislation
Medical Debt Credit Reporting Restrictions
6. insideARM - Medical Debt Legislation
Washington, D.C. Medical Debt Law
Regulatory note: This newsletter is industry and operational commentary, not legal advice. Federal and state requirements vary by product, jurisdiction, and business model. Laws and regulatory guidance change. Verify current requirements with qualified legal counsel before changing lending, reporting, data-use, underwriting, or collection practices. Illustrative financial examples are hypothetical and do not represent measured industry outcomes or guaranteed results.
|